Published by:
Prateek Ahuja
Like this article?
Fed rates are up. What does that mean for UAE mortgage rates?
If you’ve been thinking about buying a property in the UAE and getting a mortgage, the latest interest rate decision is worth paying attention to. And if a purchase is already on your mind, understanding your mortgage options in the UAE now could help you make your move before borrowing costs change further.
The US Federal Reserve has increased interest rates by 0.25 percentage points, taking its target range to 3.75%–4.00%.
Following the Fed’s decision, the Central Bank of the UAE (CBUAE) increased its Base Rate from 3.65% to 3.90%, effective 17 September 2026.
But what does a rate increase in the US have to do with your mortgage in Dubai or the rest of the UAE?
Quite a lot.
Key takeaways
The US Federal Reserve has increased interest rates by 0.25 percentage points.
The UAE Central Bank subsequently increased its Base Rate from 3.65% to 3.90%.
Changes in the UAE interest rate environment can influence mortgage rates offered by banks.
Variable-rate mortgages can be particularly sensitive to changes in EIBOR.
A relatively small difference in your mortgage rate can have a noticeable impact on your monthly repayment.
If you’re planning to buy, getting mortgage pre-approval in Dubai now can help you understand your borrowing capacity and the mortgage options currently available to you.
Why do US interest rates affect UAE mortgage rates?
It starts with the UAE dirham.
The UAE dirham is pegged to the US dollar. Because of this relationship, monetary policy in the UAE tends to closely follow changes in US interest rates.
So when the US Federal Reserve changes rates, the UAE Central Bank will often make a corresponding change to its Base Rate.
The chain is fairly simple:
Fed rates increase → UAE Base Rate increases → borrowing conditions change → UAE mortgage rates can be affected
This does not mean every UAE bank will immediately increase every mortgage rate by exactly 0.25%.
Banks determine their mortgage pricing based on several factors, including market rates, funding costs, the mortgage product and the borrower’s financial profile.
But when the broader cost of borrowing increases, mortgage rates can move too.
So, will UAE mortgage rates increase?
They can.
The impact depends partly on the type of mortgage you have or are applying for.
If you have a variable-rate mortgage
Many variable-rate mortgages in the UAE are linked to EIBOR, or the Emirates Interbank Offered Rate.
Think of EIBOR as a benchmark used by banks when pricing certain loans.
A variable mortgage may, for example, be priced as:
EIBOR + the bank’s margin
If EIBOR increases, the interest rate on an EIBOR-linked mortgage can increase when the rate is reset, depending on the terms of the mortgage.
That can result in a higher monthly repayment.
If you have a fixed-rate mortgage
If you already have a fixed mortgage rate, your rate will generally remain unchanged for the duration of the agreed fixed period.
Once that fixed period ends, however, your mortgage will move according to the terms agreed with your bank, which could expose you to the rates available at that time.
If you’re applying for a new mortgage
This is where the latest rate movement becomes particularly relevant.
The mortgage rate you see today is not necessarily the mortgage rate that will be available weeks or months from now.
Banks can adjust their mortgage products and pricing as market conditions change.
So, if you’re already planning to buy a property, delaying your mortgage application could mean applying in a different interest-rate environment.
What can even a 0.5% difference in your mortgage rate mean?
Half a percentage point may not sound significant.
Over a long-term mortgage, however, it can add up.
Consider a simplified example of a AED 1 million mortgage over 25 years.
At an interest rate of 4%, the monthly repayment would be approximately AED 5,278.
At 4.5%, it would be approximately AED 5,558.
That’s around AED 280 more every month, or approximately AED 3,360 more a year.
The actual amount you pay will depend on your mortgage amount, tenure, rate structure, fees and other terms, but the example shows why a 0.5% difference in your mortgage rate matters over the life of a home loan.
Thinking about buying? This is where mortgage pre-approval matters
If you’ve been waiting to start your property search or mortgage journey, the latest rate movement gives you a reason to understand your options sooner.
A mortgage pre-approval gives you an indication of how much a bank may be willing to lend based on your financial profile.
It can help you understand:
How much you may be able to borrow
Your approximate property budget
The mortgage rates and options currently available to you
Your estimated monthly repayment
How much down payment you may need
Which banks and mortgage products may suit your profile
Instead of looking at properties first and figuring out financing later, you can start your search knowing what may actually be within your budget.
If you’re new to the process, our complete guide to mortgage pre-approval in Dubai explains how pre-approval works and what to expect next.
Can mortgage pre-approval help you secure a rate?
This depends on the individual bank and mortgage product.
A mortgage pre-approval does not automatically guarantee that a particular interest rate will be locked across every UAE bank. Rate validity and final mortgage pricing are subject to the lender’s terms and final approval.
However, starting the process now allows you to see the mortgage options and rates currently available to you and puts you in a better position to move forward while those options are available.
That matters in a changing rate environment.
If you wait several weeks or months before even starting your mortgage application, the rates and products available at that point may be different.
Why waiting could cost you
When mortgage rates are moving, it can be tempting to wait and try to predict what happens next.
Will rates come back down? Will they increase again? Will banks change their offers?
The problem is that nobody knows exactly what rates will be when you eventually decide to buy.
If you already know that you want to purchase a property, the more useful question may be:
What mortgage can I get today?
Getting pre-approved gives you that answer.
You know your approximate borrowing capacity. You understand the rates currently available. You have a clearer property budget. And when you find the right home, you’re already further along in the mortgage process.
Does a Fed rate hike mean UAE property prices will fall?
Not necessarily.
Interest rates are only one factor affecting UAE property prices.
Prices can also be influenced by supply and demand, population growth, transaction activity, new property supply, investor demand, rental yields and the performance of individual communities.
Higher mortgage rates can make borrowing more expensive for some buyers, but that does not automatically translate into lower property prices.
That’s why buyers should look at both sides of the equation: the property they’re buying and the cost of financing it.
If you’re buying your first property, our first-time home buyer guide in Dubai covers the wider journey, from establishing your budget and getting pre-approved to finding the right property.
What should UAE homebuyers do now?
If you’re considering buying a property with a mortgage, you don’t need to wait until you’ve found the perfect home to start thinking about financing.
Start with your numbers.
Understand how much you can borrow, what your monthly repayments could look like and what mortgage rates are currently available to you.
The latest Fed rate hike has already been followed by an increase in the UAE Base Rate. As market conditions change, banks can adjust their mortgage pricing too.
The rate available today may not necessarily be available later.
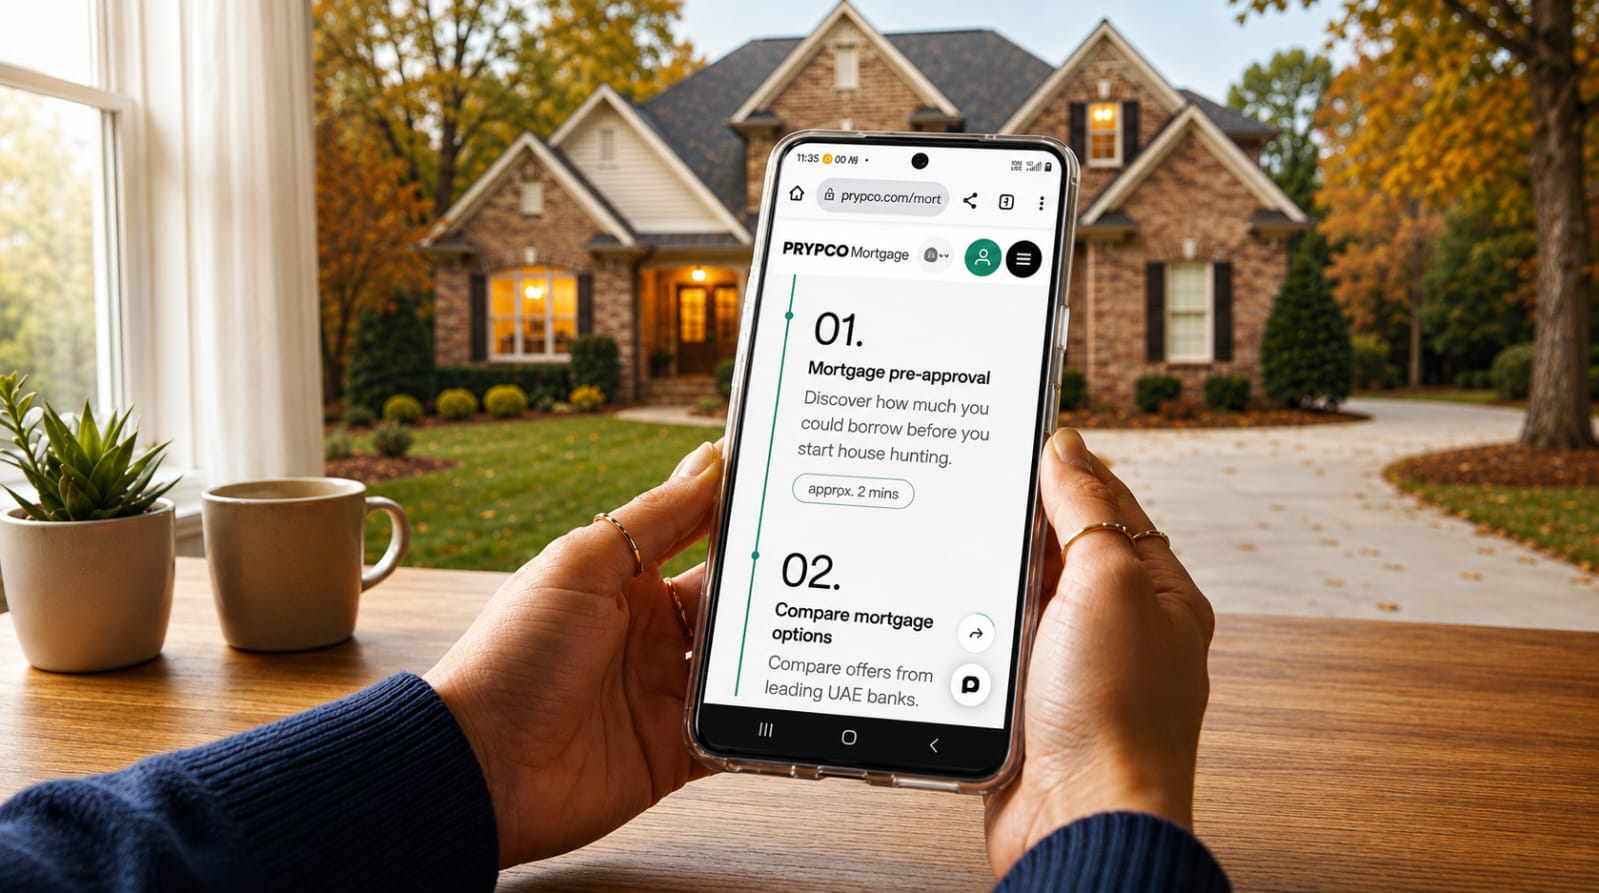
With PRYPCO Mortgage, you can compare mortgage options from leading UAE banks and start with a quick mortgage pre-approval.
Don’t wait for rates to move again. Find out what mortgage options are available to you today. Get mortgage pre-approval
Frequently Asked Questions (FAQs)
Why does the Fed interest rate affect mortgages in the UAE?
The UAE dirham is pegged to the US dollar, so the UAE Central Bank's monetary policy tends to closely follow US interest-rate movements. Changes in the UAE interest-rate environment can then affect borrowing costs, including mortgage pricing.
Did UAE interest rates increase after the latest Fed decision?
Yes. Following the latest Fed decision, the UAE Central Bank increased its Base Rate by 25 basis points, from 3.65% to 3.90%, effective 17 September 2026.
Will UAE mortgage rates increase by 0.25% too?
Not necessarily. Banks set their mortgage rates based on several factors, so a 0.25 percentage point increase in the UAE Base Rate does not mean every mortgage rate will automatically increase by the same amount.
What is EIBOR?
EIBOR stands for the Emirates Interbank Offered Rate. It is a benchmark used in the UAE and can be used to determine the interest rate on variable-rate mortgages and other lending products.
Should I get mortgage pre-approval before looking for a property?
Getting mortgage pre-approval in Dubai before your property search can help you understand how much you may be able to borrow, your approximate monthly repayments and the property budget you can realistically consider. It can also put you in a stronger position to move once you find a property.
Does mortgage pre-approval lock my interest rate?
Not automatically. Whether a rate can be secured for a particular period depends on the bank, mortgage product and applicable terms. However, getting pre-approved now helps you understand the mortgage rates and products currently available to you rather than waiting until later when market pricing may have changed.
How can I compare mortgage rates in the UAE?
With PRYPCO Mortgage, you can compare mortgage options from leading UAE banking partners and get support throughout the mortgage process.